The New Ecosystem of Rural Finance
Why affordable capital still fails to reach small farmers despite record agricultural lending, and how fintech is reshaping rural finance
SK Singh
Agricultural lending in India has now entered its third phase. The first phase was driven by banks under the Priority Sector Lending (PSL) framework. This was followed by the rise of Non-Banking Financial Companies (NBFCs). Today, in the third phase, financial technology (fintech) companies are rapidly emerging as key players in meeting the credit needs of the farm sector. Beyond farmers, fintech firms are extending credit to Farmer Producer Organisations (FPOs), dairy, livestock and fisheries enterprises, as well as agri-entrepreneurs. Technology has not only simplified the lending process but has also made it more transparent. However, experts caution that this emerging agricultural credit ecosystem requires close regulatory oversight to prevent it from turning into a financial ‘bubble’ in the future.
The rise of fintech has been driven by several structural changes. According to the Economic Survey 2025-26, the share of non-institutional credit in agriculture declined dramatically from 90 percent in 1950 to just 23.4 percent in 2021-22. This reflects a significant reduction in farmers’ dependence on moneylenders and a strengthening of the formal financial system.
The Economic Survey also highlights a critical imbalance. Agricultural activity, PM-KISAN beneficiaries and institutional credit are unevenly distributed across regions. For instance, Central India accounts for nearly 30 percent of the country's gross cropped area and has the largest number of PM-KISAN beneficiaries. Yet, the region received only 14.7 percent of the total disbursement under the Modified Interest Subvention Scheme (MISS). This indicates that institutional agricultural credit remains unevenly distributed. It is this gap that NBFCs initially sought to address, and which fintech companies are now trying to bridge at a much faster pace.
The Rise of Technology-Based Lending Platforms
Digital lending platforms are using digital identity, e-KYC, Aadhaar, UPI, Account Aggregator frameworks and alternative data to reach farmers who were previously underserved by conventional banking channels. These innovations have significantly reduced loan approval timelines while making the lending process more efficient.
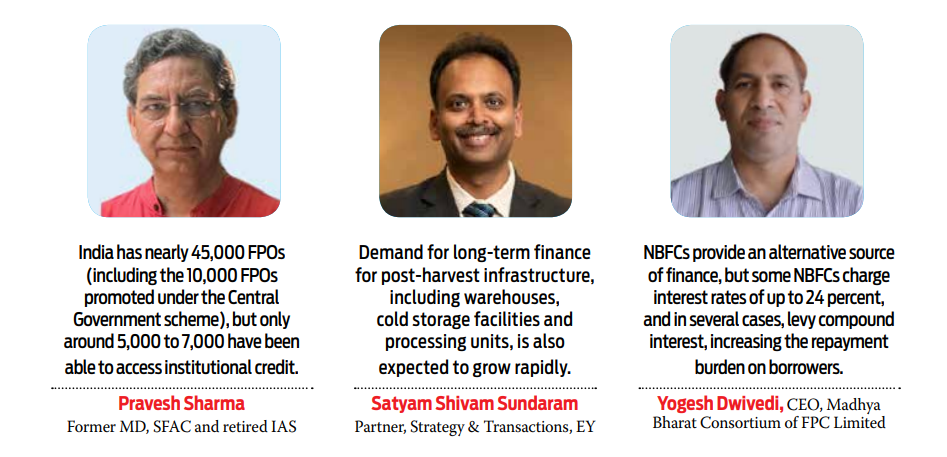
According to Satyam Shivam Sundaram, Partner, Strategy & Transactions at EY, “Fintech has made credit far more accessible. It has enabled the creation of a digital persona for every borrower and introduced greater transparency into the lending process. Today, lenders have sophisticated tools to evaluate borrowers and assess credit risk much more accurately. Agricultural credit, which was earlier largely push driven because of regulatory and government mandates, has increasingly become pull-driven, with demand now emerging from borrowers themselves.”
He explains that lending decisions primarily depend on two factors: the credibility of the borrower - whether an individual or an institution - and the viability of the project for which credit is sought. Today, e-KYC, Aadhaar-based verification and digital credit histories provide transparent information that allows lenders to evaluate borrowers’ past financial behaviour and estimate lending risks with much greater confidence.
Sundaram believes that FPOs, Self-Help Groups (SHGs), cooperatives and agri-entrepreneurs will play an increasingly important role in India's agricultural value chain over the coming years. Consequently, demand for long-term finance for post-harvest infrastructure, including warehouses, cold storage facilities and processing units, is also expected to grow rapidly.
Technology Alone Is Not Enough
However, technology alone cannot solve the structural challenges of agricultural finance. Pravesh Sharma, former Managing Director of the Small Farmers’ Agribusiness Consortium (SFAC) and a retired IAS officer, believes that the biggest challenge remains ensuring adequate capital for Farmer Producer Organisations.
According to Sharma, India has nearly 45,000 FPOs (including the 10,000 FPOs promoted under the Central Government scheme), but only around 5,000 to 7,000 have been able to access institutional credit. The primary reason is that processing small-ticket agricultural loans is expensive for banks, making this segment commercially unattractive.
Sharma notes that while NBFCs have attempted to fill this financing gap, they face limitations of their own. Since they largely depend on banks for funding, their lending rates often range between 18 and 20 percent. As a result, FPOs typically approach NBFCs for their initial loans because of more flexible lending norms. However, once they establish a credit history, they generally shift to banks, where borrowing costs are significantly lower.
Drawing from his experience as a recent board member of agri-financing company Samunnati, Sharma points out that the company used to provide loans of up to Rs 500,000 to newly formed FPOs within a week of their incorporation based on cash-flow assessments rather than collateral. However, nearly 80 percent of these FPOs subsequently obtained their second loan from banks. In his view, the biggest challenge facing FPOs is not market access but the availability of affordable working capital. This is why he believes fintech has only limited relevance for FPO financing.
Budget Allocations
•Modified Interest Subvention Scheme (MISS): Allocation of Rs 22,600 crore has been made for FY2026-27, unchanged from the previous year. Government spent Rs 17,812 crore on the scheme in FY2024-25.
•PM-Kisan Samman Nidhi: Allocation for FY2026-27 has been kept unchanged at Rs 63,500 crore, the same as the previous year. Actual expenditure under the scheme stood at Rs 66,121 crore in FY2024-25.
The Growing Role of Non-Bank Credit in India's Agrifood Economy
Five minutes. That’s how long it takes for a farmer to get a loan approved after walking into one of Arya.ag’s warehouses. That’s faster than a quick commerce order in some of the fastest Indian cities. A grain farmer arrives with freshly harvested grains, the produce is weighed, AI-enabled scanners assess its quality, and within minutes, a loan worth 60-75% of its value is credited to the farmer's bank account. There’s no paperwork, and no weeks worth of waiting.
The grain stays safely in storage, giving the farmer the freedom to sell later, when market prices improve rather than immediately after harvest.
Arya.ag is one example of a broader shift taking place across India's credit ecosystem for agriculture and allied activities. India's agricultural credit has expanded significantly in recent years, highlighting the rising demand for capital across the rural economy. While scheduled commercial banks continue to account for the majority of agricultural lending; NBFCs, fintechs, and embedded finance platforms are increasingly addressing financing needs across agriculture and allied sectors by developing products tailored to specific value chains and business models.
As the agrifood economy has become more specialized, so have its capital needs. The financing needs of the sector now extend far beyond seasonal crop loans. Farmers increasingly require capital not only to purchase inputs, but also to store produce after harvest, invest in mechanization, diversify into allied activities such as dairy and fisheries, and manage cash flows throughout the year. At the same time, Farmer Producer Organizations (FPOs), warehouses, processors,
The Cost of Credit Remains a Concern
Yogesh Dwivedi, Chief Executive Officer of the Madhya Bharat Consortium of Farmers Producer Company Limited, offers another perspective. He argues that nearly 60 percent of farmers still do not receive adequate credit from the formal banking system. In such cases, NBFCs provide an alternative source of finance, but often at a steep cost. According to him, some NBFCs charge interest rates of up to 24 percent, and in several cases, levy compound interest, increasing the repayment burden on borrowers. Given the inherent uncertainty of agriculture, such borrowing can push farmers into a debt trap.
Dwivedi points out that farming does not generate daily cash flows. If a farmer borrows at high interest for a crop that will be harvested only after four to six months, repayment becomes difficult if adverse weather or weak market prices affect production.
He believes that small farmers need much more than access to credit. They also require technical guidance, market linkages and risk management support to improve farm incomes and reduce financial vulnerability.
At the same time, he acknowledges that NBFCs play a constructive role in helping farmers and FPOs build a formal credit history. They also provide an important source of interim finance when bank loans are delayed, enabling FPOs to continue their agricultural operations without interruption.
Improving the Quality of Agricultural Credit
Climate change has emerged as a new challenge for agricultural finance. Unseasonal rainfall, heat stress, emerging crop and livestock diseases, and increasing production uncertainty are raising credit risks for lenders. According to Satyam, loans and insurance are likely to become increasingly complementary in the coming years. Advances in satellite imaging and digital data now make it possible to assess crop losses at the individual farm level, enabling better management of both insurance claims and credit risk.
One of fintech’s biggest strengths lies in its low operating costs and datadriven risk assessment capabilities. Digital documentation, e-KYC, online payments and alternative data sources have significantly accelerated loan disbursement. As a result, fintech companies are no longer confined to consumer lending; they are increasingly designing financial products for agriculture, livestock, dairy, fisheries and rural enterprises. They are promoting financial inclusion through innovative products such as warehouse receipt financing, farm equipment loans, seasonal working capital and colending partnerships with banks.
Even so, experts believe that technology alone cannot address the structural challenges of agricultural finance. If credit remains expensive or repayment terms fail to match the cashflow cycles of farming, digital lending platforms will not provide a sustainable solution for farmers. The next phase of agricultural finance, therefore, is not merely about expanding the volume of credit but about improving its quality.
A farmer benefits when an FPO has the capital to aggregate produce, when a processor can purchase immediately after harvest, when a warehouse can finance stored grain, or when an exporter has the liquidity to fulfill an order. Increasingly, the efficiency of agricultural markets depends on capital flowing seamlessly across the entire value chain.
exporters, agri-input retailers, and logistics providers require working capital to procure produce, finance inventory, bridge receivables, and keep agricultural supply chains moving. Rather than replacing banks, the emerging non bank institutions expand the reach of formal finance by serving financing needs that require greater speed, flexibility, or specialized underwriting.
A farmer benefits when an FPO has the capital to aggregate produce, when a processor can purchase immediately after harvest, when a warehouse can finance stored grain, or when an exporter has the liquidity to fulfill an order. Increasingly, the efficiency of agricultural markets depends on capital flowing seamlessly across the entire value chain.
Arya's model is a great example of how non bank credit benefits multiple touchpoints in the agrifood ecosystem. Warehouse receipt allows produce to be stored instead of sold immediately, giving farmers greater flexibility over when they sell. Working capital reaches the farmer when it is needed most, while warehouses remain utilized, processors gain more reliable procurement, and banks are able to participate through lending partnerships. A single financing product improves outcomes across multiple participants in the agricultural value chain. This is why non-bank credit has become increasingly important to India's agrifood economy. Its role is to broaden the financial system's ability to serve an increasingly complex and interconnected sector.
As agriculture evolves from a production-centric industry into an integrated agrifood economy, financing cultivation alone is no longer enough. The next phase of agricultural growth will depend on financing every stage of value creation: from the purchase of inputs to the movement of food from farm to consumer. Banks will remain central to that journey, while NBFCs and inclusive fintechs are emerging as the connective link that makes the entire ecosystem more efficient, resilient, and inclusive.
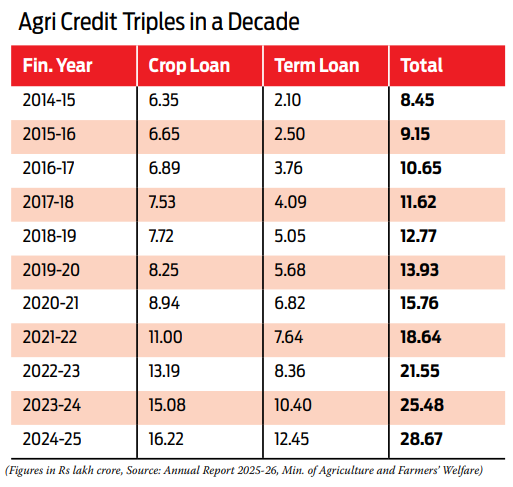
India's agricultural economy is entering a phase where the demand for capital is rising rapidly. FPOs, agri-startups, agri-processing, dairy, fisheries and agricultural infrastructure are expected to become major engines of rural growth in the years ahead. Meeting their financing needs will require a combination of traditional banking and modern fintech solutions. Equally important, however, will be a balanced regulatory framework. As Satyam cautions, “If fintech-led agricultural lending expands without adequate oversight, it could eventually turn into a financial bubble. Transparency, public disclosure of data and responsible lending practices must therefore be given the highest priority.”
It is evident that the next chapter of agricultural credit in India will not be defined merely by the volume of lending. Its real success will be measured by whether small farmers, FPOs and rural entrepreneurs gain equitable access to affordable, timely and sustainable financial services. Only then can the expansion of agricultural credit truly become a foundation for inclusive rural development.
RNI No: DELBIL/2024/86754 Email: [email protected]